Buying
Build a plan for financing, touring, offers, inspections, and closing—without losing sight of what you actually need from a home.
See the buying process
Ann Arbor · Ypsilanti · Michigan
Thoughtful buyer and seller representation for the homes, neighborhoods, and next chapters that matter most.

Rooted in Washtenaw County
From established Ann Arbor streets to Ypsilanti’s distinctive historic homes, every move deserves a strategy shaped around the person making it.
Expect direct communication, careful preparation, and a process that keeps the next decision understandable.
Learn about the approachChoose your path
Build a plan for financing, touring, offers, inspections, and closing—without losing sight of what you actually need from a home.
See the buying processPrepare your property, understand the market, review offers with context, and move toward closing with a clear strategy.
See the selling processOrganize your search, compare total move-in costs, prepare for applications, and get help asking the right questions.
See the rental processFind official Michigan and nationwide guidance on down payment help, mortgages, housing assistance, refinancing, and more.
Explore the resource centerLocal representation
Real estate can move quickly. The guidance around it should stay calm, candid, and centered on your goals.


The approach
I help buyers and sellers make sense of the moving pieces, ask stronger questions, and choose the next step with confidence.
That means listening before recommending, explaining the tradeoffs behind each decision, and keeping communication clear from the first conversation through closing.
Serving residential buyers and sellers in Ann Arbor and Ypsilanti, Michigan.
For renters
Share what you need, receive rental options that fit, and get help asking the questions that matter before you apply.

Your rental plan
Melanie helps renters in Ann Arbor, Ypsilanti, and surrounding Washtenaw County organize their search, compare options, and communicate with property representatives.
Start by sharing your preferred areas, move date, budget, household needs, and must-haves. Melanie can then follow up with next steps and help you prepare for showings and applications.
Rental listings, pricing, availability, fees, and application requirements can change. Confirm details with the property representative before applying.
How it works
Share your areas, move date, monthly budget, bedroom count, pets, occupants, and priorities through the conversational intake.
Compare available rentals with attention to total move-in costs, included utilities, lease terms, and application requirements.
Narrow the search to the strongest matches so questions and showing requests stay focused.
Gather requested income, employment, credit, identification, and pet information before submitting an application.
Rental intake form
Prefer typing it all out instead of chatting? Fill in the form below — it comes straight to Melanie so she can match you with rental options that fit.
For buyers
Strong decisions begin before the first showing—with clear priorities, realistic numbers, and a process built around you.
A steady process
The right home is only part of the goal. The path to it should be informed, organized, and responsive to the market.
Talk about buyingClarify priorities, preferred areas, timing, and the monthly budget that feels sustainable.
Coordinate financing readiness and the documents needed to write a strong offer.
Compare homes with attention to condition, fit, location, and long-term value to you.
Review terms, contingencies, and strategy before making a decision.
Navigate inspection, appraisal, lender milestones, final walk-through, and closing.
Buyer guide
A little preparation makes it easier to compare homes, financing, and tradeoffs without letting urgency make the decision for you.
Look beyond the purchase price. Estimate principal, interest, property taxes, homeowners insurance, association dues, utilities, and a realistic repair reserve. Keep enough cash available for closing costs and the first surprises of ownership.
Interest rate matters, but so do APR, points, lender fees, mortgage insurance, cash to close, and whether the rate is locked. Review Loan Estimates side by side and ask what can still change before closing.
An independent inspection can help you understand condition, likely maintenance, and questions for specialists. Read the report closely and make repair or concession decisions in the context of your contract and priorities.
Programs and eligibility can change. Confirm current terms with the program administrator and your lender.
Start well
Bring your questions—even if you are months away or still deciding whether buying is the right next move.
Email about buyingAvailable now
A curated look at active homes on the market in Ann Arbor and Ypsilanti. Tap any home to browse its photos, then reach out for a private showing.
For sale
Tap a home to see all of its photos. Availability changes quickly — call or text for the latest.
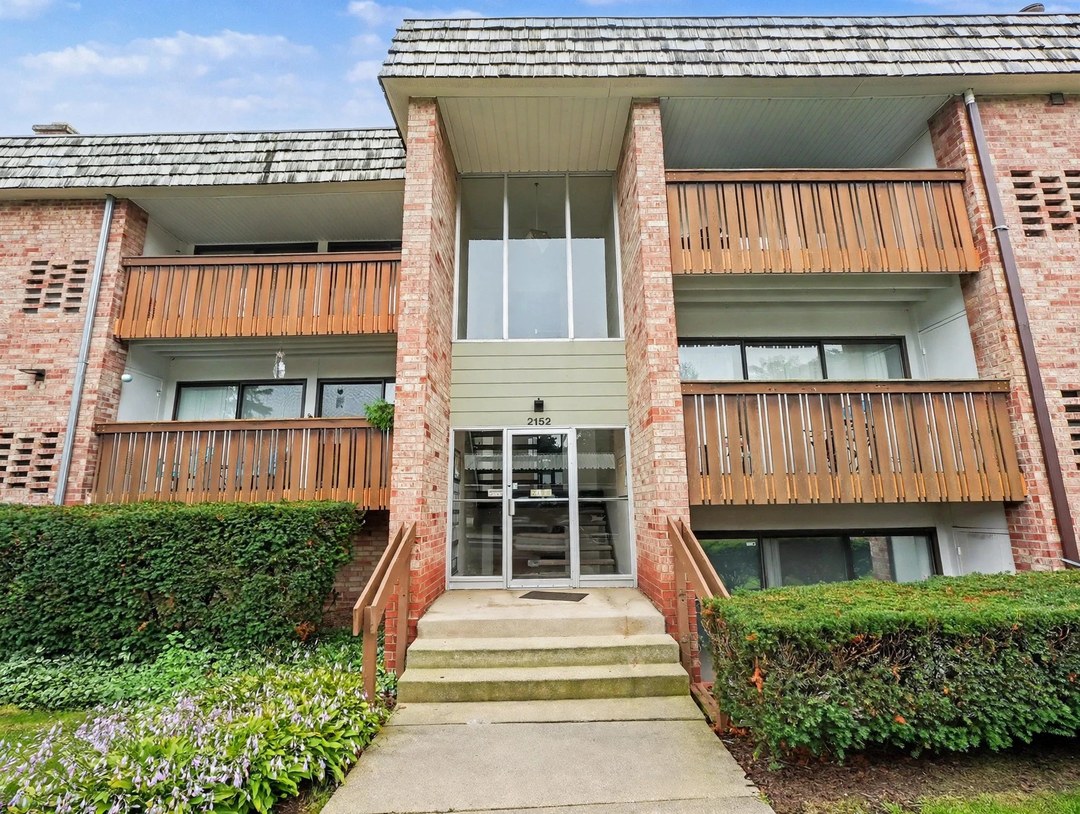 View photos
Low-maintenance living in Walden Hills with a transferable home warranty good through 2027 — peace of mind included.
Ask about this home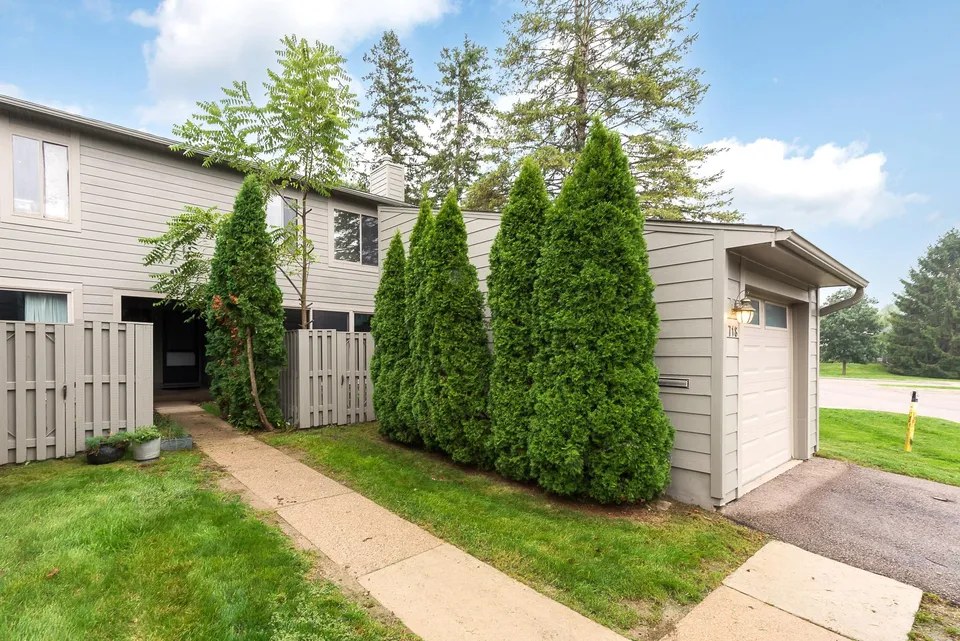 View photos
End-unit condo at Geddes Lakes with extra windows and privacy — great value in a sought-after community.
Ask about this home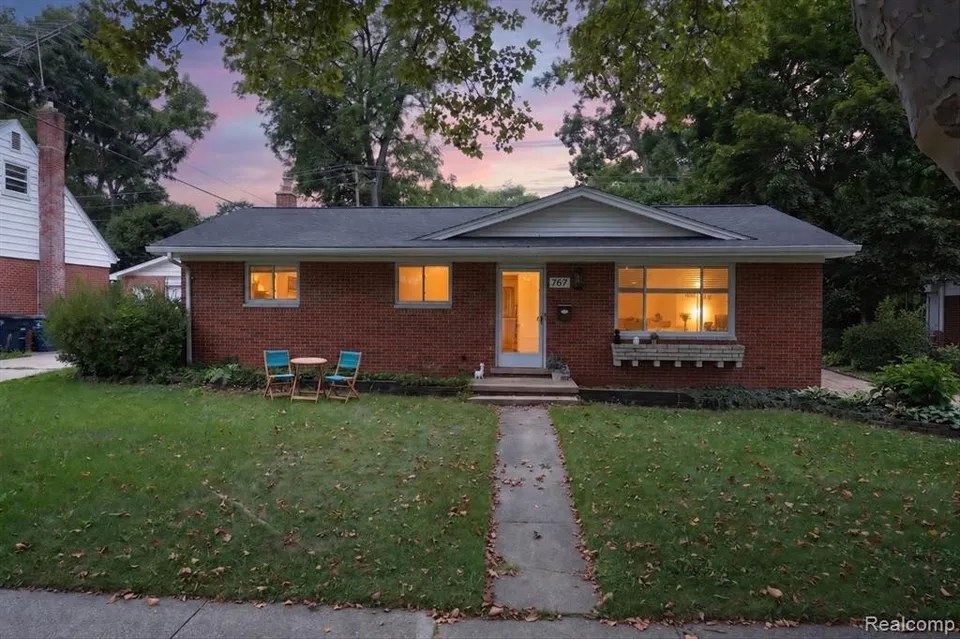 View photos
Ranch with a finished basement and 1.5-car garage in Hollywood Park.
Ask about this home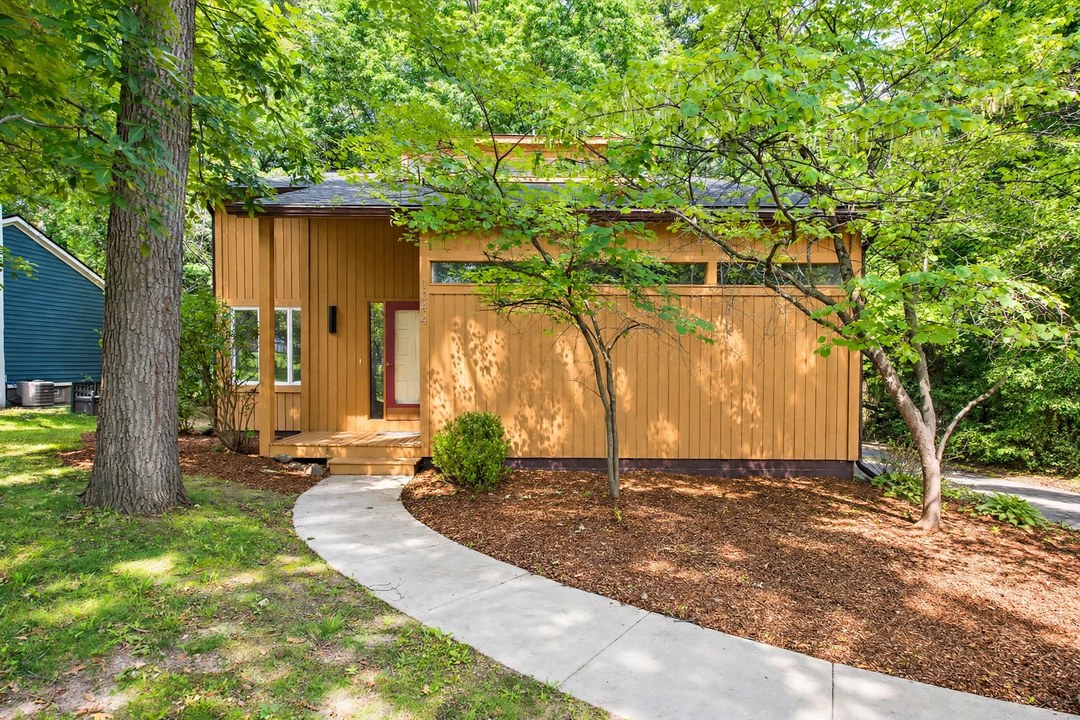 View photos
Contemporary in Newport Woods — clean lines, generous space, and a quiet established setting.
Ask about this home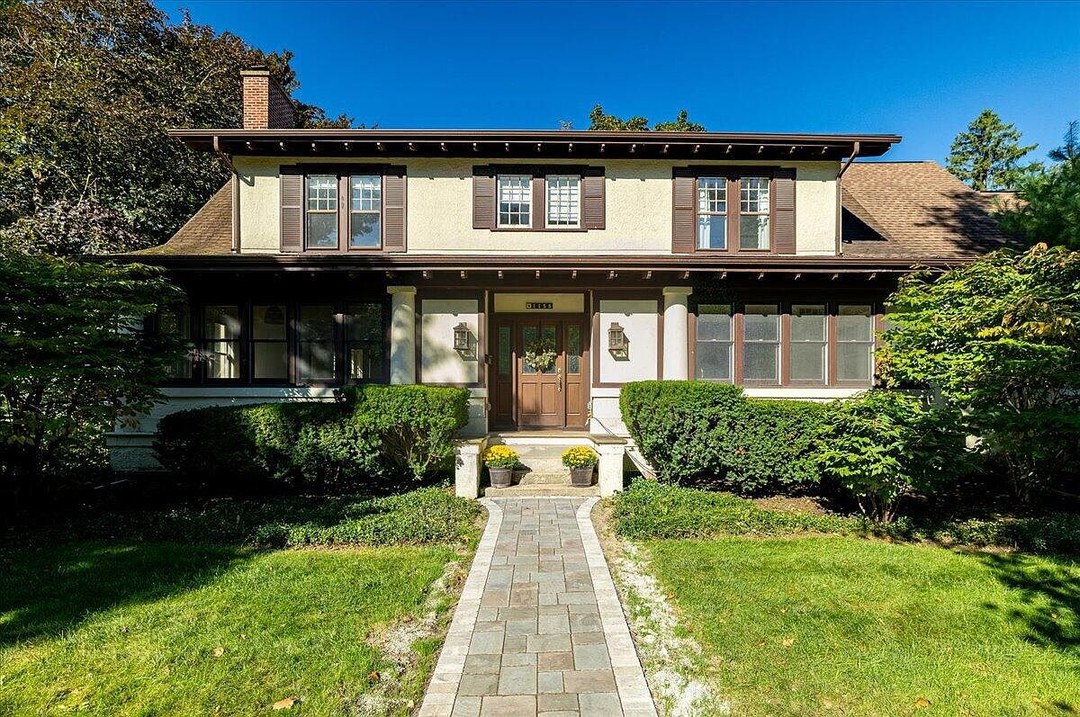 View photos
Grand 1912 Craftsman with finished basement — timeless architecture meets modern living.
Ask about this homeThese featured homes are active listings sourced from the local MLS and listed by various brokerages. Melanie can schedule your private showing and represent you as your buyer’s agent. Listing information is deemed reliable but not guaranteed — availability, pricing, and details may change. Call or text (269) 357-9844 for the latest.
For sellers
A strong sale starts with preparation, positioning, and a plan for the decisions that arrive after the listing goes live.
Discuss your timing, property, priorities, and what a successful move looks like.
Review relevant market context and decide on pricing and launch strategy.
Prioritize presentation details that help buyers understand the home’s strengths.
Compare offer price, financing, contingencies, timing, and overall risk.
Coordinate contract milestones and closing while keeping your next step in view.
Seller representation
A price is one part of an offer. Good representation helps you weigh the whole picture and move forward with fewer surprises.
Talk about sellingSeller guide
The cleanest transaction usually starts with early preparation: understanding the property, the likely buyer questions, and the terms that matter to your next move.
Address visible maintenance items, simplify rooms, improve lighting, and gather records for important systems and past work. The goal is not to erase the home’s character—it is to help buyers see the property clearly.
Compare financing, earnest money, inspection and appraisal terms, requested concessions, possession, and closing timing—not only price. The strongest offer is the one whose value and risk fit your priorities.
Keep contract dates visible, respond quickly to document requests, and plan utilities, keys, final cleaning, and your move. If your purchase and sale overlap, discuss timing and backup options before accepting terms.
These resources are educational and do not replace tax or legal advice for your specific transaction.
A conversation about your timing and goals is the best place to begin. No generic valuation replaces seeing the property and understanding your plan.
Email about sellingMichigan housing guidance
Start with official program details, practical preparation steps, and direct links to the organizations responsible for the information.
For buyers
Michigan buyers may have several paths to explore. Eligibility is determined by the program and lender, so use these summaries to prepare questions—not to self-approve.
MSHDA’s MI 10K Down Payment Assistance program provides up to $10,000 toward down payment, closing costs, and prepaid expenses.
Source: Michigan State Housing Development Authority, reviewed September 18, 2026.
The MI Home Loan is the MSHDA mortgage used with MI 10K DPA. MSHDA lists these current statewide baselines:
Source: Michigan State Housing Development Authority. Confirm income, household, property, and lender requirements before applying.
This 30-year MSHDA mortgage reduces the borrower’s mortgage rate by one percentage point for qualifying first-time buyers.
Source: Michigan State Housing Development Authority. Availability and lender participation should be confirmed directly.
The $25,000 First-Generation Down Payment Assistance pilot is not accepting applications. MSHDA states that all funds were exhausted and no waitlist is available.
This closed pilot is shown only to prevent confusion with older articles or advertisements.
FHA loan basics
FHA insures loans made by approved lenders; it does not lend money directly. A lender may set requirements above FHA’s policy minimums.
For one-unit properties with FHA case numbers assigned on or after January 1, 2026, the national floor is $541,287 and the high-cost ceiling is $1,249,125. Your county’s limit may differ.
FHA loans include upfront and annual mortgage insurance premiums. Debt-to-income, income documentation, property condition, and lender overlays also affect approval.
Credit building
Credit improvement takes time. These steps come from CFPB and major-credit-bureau guidance for future homebuyers.
Payment history matters most. Use reminders or automatic payments so every bill is paid by its due date.
Reduce credit utilization and avoid getting close to the limit on revolving accounts.
Apply slowly, avoid taking on debt you do not need, and do not close older no-fee cards solely because they are unused.
Review all three credit reports and dispute inaccurate information early, because corrections can take time.
Free credit reports are available through AnnualCreditReport.com. For a personalized plan, find a HUD-approved housing counselor or call 1-800-569-4287. Be cautious of companies promising to “fix” credit, especially when they charge upfront fees.
A recommended first conversation
Melanie recommends Loren Yates as one lender to speak with about prequalification and affordability. This is a recommendation, not a requirement—you may choose any lender, and comparing offers is encouraged.
Verified FHA options
These lenders were verified as offering FHA loans. Inclusion is informational, not an endorsement, and products may vary by location and borrower.
Ask each lender for a Loan Estimate and compare APR, points, lender fees, mortgage insurance, cash to close, and rate-lock terms. Rates were intentionally not listed because they change.
Official video guides
From the official MSHDA YouTube channel.
Watch on YouTubeFrom HUD’s official YouTube channel.
Watch on YouTubeFrom the official CFPB YouTube channel.
Watch on YouTubeFor renters
A focused rental search starts with a realistic monthly budget, a move date, preferred areas, bedroom needs, pet details, and the application documents a property representative may request.
For sellers
A useful seller conversation begins with your goals, timing, property condition, and what the next move needs to accomplish. Melanie can help you understand the preparation and market context before deciding how to proceed.
The seller intake experience is still being decided, so there is no long form to complete. Start with a direct call, text, email, or chat.
Important note
This page is for general education. Program rules, limits, lender standards, and availability can change. Confirm current details and your eligibility with a licensed lender or MSHDA before acting.
You may choose any lender. A recommendation or link on this page does not require you to use that provider and does not guarantee approval, terms, or an outcome.
Let’s connect
Buying, selling, or still sorting out the possibilities? Start with a direct conversation.

Share your home-search plans one question at a time, by typing or using your microphone.
Have a quick question? Call or text Melanie directly.
Share your timeline, preferred area, and how you would like to be contacted.
Chat with Melanie’s assistant
Choose buying, selling, renting, or resources. The assistant will guide you to the right questions or information.
Broker phone: +1 734-353-0206
Serving Ann Arbor and Ypsilanti, Michigan.